
Wise Business Account Review 2026: Fees, FX Rates, Cards and Interest — Who Should (and Shouldn't) Use It
Last updated: September 2026
💬 Disclosure: Some links in this article are affiliate links. We may earn a small commission when you complete a purchase at no extra cost to you. This helps us keep our content free, and it does not affect the integrity of our recommendations.
Here is what the first month with a Wise Business account actually looks like. Day one: you register with your business email, upload a registration document, a proof of address, and ID for each owning partner, then you wait — verification is not a wallet-app formality for a listed financial institution, and it can run from days to a couple of weeks depending on how complete your file is. Somewhere in week one or two: approval lands, local account details go live in USD, EUR, and GBP, and your first client abroad pays you as if you were a domestic company. By month's end, the pattern that justified the account is visible in a single statement: inbound client money separated from local operating costs, supplier subscriptions paid in each vendor's own currency, and a mid-market exchange rate you can verify independently on any neutral rate site. That is the product in one paragraph — and this review takes it apart to see where it earns its keep and where it disappoints.
The 2026 reason to evaluate it seriously: Wise is no longer the 2011 transfer app. It is a London-listed company (LSE: WISE, since 2021) building a business-banking stack — physical and virtual team cards, invoicing with payment links, batch payouts to a thousand recipients in one click, and a North American expansion that added a Chequing account in Canada in September 2026. Competitor reviews multiplied through the year, which usually means a product has become a default worth auditing. This review is the audit: fees, features, verification reality, five genuine weaknesses, and an honest shortlist of who should open something else instead.
Quick verdict: who this account is for
| Criterion | What you get |
|---|---|
| Monthly fees | None, after a one-time setup fee in some countries |
| Opening cost | One-time setup fee where applicable; free registration elsewhere |
| Currencies | Balances in 22 currencies; 21-currency instant transfers between Wise users |
| Receiving money | Local account details in USD, EUR, and GBP |
| Exchange rate | Mid-market rate with a disclosed, route-dependent conversion fee shown before you confirm |
| Batch payouts | Up to 1,000 recipients per batch |
| Cards | Physical and virtual team cards with per-person spend controls |
| Credit | None — the account runs on loaded balance only |
Three profiles fit this cleanly: small agencies and professional freelancers invoicing clients abroad in USD, EUR, or GBP; e-commerce operators paying multi-currency suppliers who want better economics than correspondent-bank transfers; and startups that need local receiving details in several markets without opening a bank account in each one. Three profiles should stop reading and pick another tool: businesses needing credit facilities or overdrafts, single-currency domestic businesses with no cross-border flows, and anyone who requires branch banking with a relationship manager and paper cheques.
What Wise Business actually is
Wise was founded in London in 2011 as TransferWise by Kristo Käärmann and Taavet Hinrikus, and grew from a cheap-transfer app into a global financial services company listed on the London Stock Exchange since 2021. The core idea of the business account is jurisdictional arithmetic: instead of opening a bank account in every country you trade with, you hold local receiving details in major currencies. Your US client pays you domestically to an American account and routing number; your German client pays a EUR transfer to an IBAN; your UK client uses sort-code details. You manage every balance from one dashboard and pay each supplier in the currency they invoice you in.
Source: Wise
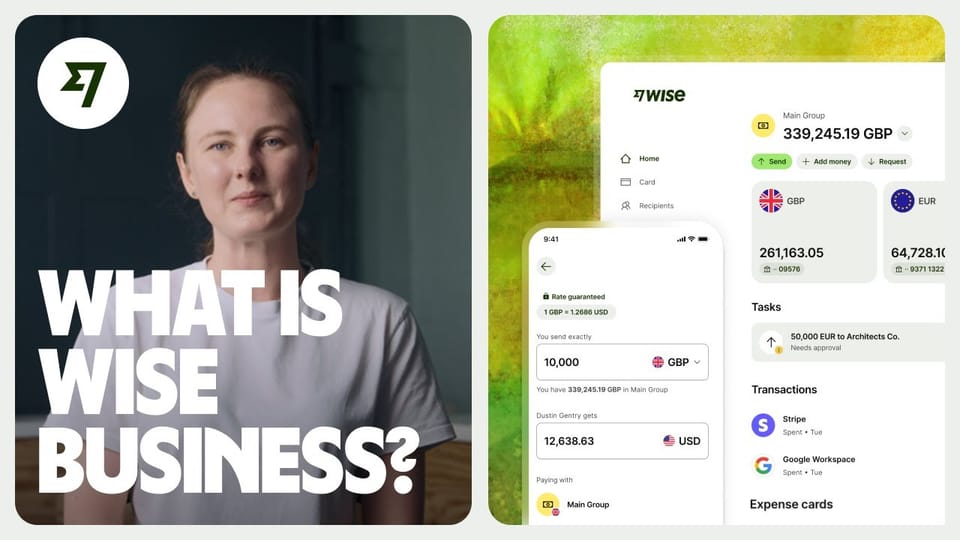
The official explainer below from the Wise Business channel covers the concept in two minutes:
Source: Wise Business on YouTube
The difference from the personal account is not just pricing. The business account is built for an entity — registered company or documented sole practitioner — and adds an administrative layer: invoicing with payment links, company cards for team members with individual limits, tiered access permissions, transaction exports into accounting software, and an API for companies that automate payouts from their own systems. It is designed to be run by several people, not one.
The fee structure: what you actually pay
Three rules govern the whole pricing model, as published on the official page. First, no monthly fee — an empty account costs nothing to keep. Second, a one-time setup fee applies to business accounts in some countries while registration remains free in others; the amount depends on your registration country and the platform displays it before you complete opening, so there is no surprise line. Third, every currency conversion runs on the mid-market rate — the reference rate visible on independent trackers — plus a small, route-dependent fee shown before you confirm. No hidden spread is layered into the rate itself.
The honest way to evaluate this is not "what is the fee" but "what arrives at the destination". Classic banks typically add a margin to the exchange rate itself and then a transfer fee on top, so a single transfer can cost a multiple of the same route through Wise on common corridors. Those deltas compound: a business making dozens of cross-currency payments a year feels them directly in margin. One structural fact also belongs here, stated plainly: registration is slower than opening a consumer wallet. A listed, multi-jurisdictionally regulated institution verifies every business's identity and documents, and incomplete files or ambiguous activities get delayed or declined. That is not a defect — it is the compliance posture that protects balances — but you should start the process weeks before you need the account live, not the day before an invoice is due.
Receiving money like a local
This is the feature that pays for the account even if you rarely convert anything. Overseas clients settle invoices the way they would pay a domestic supplier — no international wire instructions, no correspondent-bank charges deducted in transit, no "we sent it, where is it" email threads. For an agency billing European clients from outside Europe, this alone shortens the collection cycle by days and removes an entire category of payment friction. The funds land as balances in the received currency, ready to hold, convert at the mid-market rate, or spend from a card.
Batch payouts, invoicing, and payment links
Three features do the heavy lifting for operations teams. Batch payouts send up to 1,000 payments from a single file — commission runs, partner settlements, marketplace supplier payouts — turning a day of manual work into one upload. Invoicing with payment links converts billing from a reminder email into a clickable payment, with card payment collection as an option. And team cards — physical and virtual — let you assign a spending budget per person and freeze any card instantly from the dashboard, which is a cleaner control than sharing one person's card details around the company.
Security and regulation
Wise states it runs more than seven million automated checks per day to detect and prevent fraud, on top of its position as a listed company subject to disclosure and oversight in major markets. For team governance, tiered permissions mean a bookkeeper sees only what they need, an owner sees everything, and sensitive operations require additional confirmation. The professional rule regardless of provider: distribute operating liquidity between your international account and your licensed local bank rather than parking all working capital on any single platform. Our comparisons of Mercury for non-US founders and US business bank accounts for non-residents apply the same principle to other stacks.
Source: Wise
Interest on balances: Wise Assets, explained
In some regions Wise offers a feature called Wise Assets, which pays returns on balances held in certain currencies through its European entity. Two things a business owner should know. Functionally, it is optional: leaving it disabled costs nothing and removes nothing — transfers, receiving details, cards, and invoicing all work independently of it. Strategically, returns on idle balances are a treasury decision, not a default: if your policy is to keep client money and operating funds in non-interest-bearing accounts, or your jurisdiction treats such returns as taxable interest income with reporting consequences, keep the feature off and run the account purely as a payments instrument. The fee logic of the account does not depend on it in any way.
Five weaknesses to accept before you open it
A review without defects is an advertisement, so here are the real ones. First, there is no credit: no overdraft, no guarantees, no letters of credit — a business that needs those instruments needs a traditional bank alongside, permanently. Second, verification can drag for certain activities and certain registration countries, and some countries are effectively excluded from business onboarding; check availability for your registration country before anything else. Third, support is digital-first: fast in the routine cases, but there is no relationship manager, and a complex case such as a temporary review hold can take days of document exchange. Fourth, security reviews can freeze an account pending extra documents — standard practice at regulated institutions, painful when it lands mid-collection-cycle. Fifth, a purely domestic single-currency business gains nothing worth the setup: the account's entire value is the cross-border dimension.
Who should not open this account
Converting the weaknesses into profiles: skip it if you need working-capital credit; skip it if every supplier and customer is in your own country and currency; skip it if you insist on branch service with a human across a desk; and skip it if your model requires cash deposits — the account is built for digital flows and does not accept physical cash. There is also a regulatory tailwind worth noticing: tax systems themselves are moving away from large undocumented cash payments — our briefing on the UAE VAT changes from 1 October 2026 documents one such shift — which makes fully banked, traceable payment infrastructure a durable direction rather than a fashion.
Alternatives: Airwallex and Payoneer
This account is not the only serious option in its class, and the right choice depends on where your financial pain actually sits. Our full Airwallex vs Wise vs Payoneer comparison breaks the pricing down route by route, and the short version is: Airwallex leans stronger for companies wanting a broader payments stack — advanced invoicing, currency management, team spend controls, and e-commerce integrations — while Payoneer remains the popular pick for freelancers collecting from the major gig platforms. The decision rule we recommend: identify your single largest recurring cost — receiving fees, conversion spread, or expense sprawl — and pick the tool that is strongest at that specific job rather than buying an entire ecosystem for one problem. We have also published a dedicated Payoneer vs Airwallex comparison for readers comparing those two directly.
If Airwallex fits your business better, you can start here.
A four-person agency's first quarter
The following is a composite of patterns that recur in founder communities, told because it compresses a full decision cycle into one story. A four-person design agency based outside its clients' countries, billing the UK, Germany, and the US, had a familiar annual complaint: the local bank charged heavily on every inbound foreign-currency wire, applied an exchange rate visibly worse than neutral trackers, and clients grumbled about long international transfer instructions routed through their finance departments.
After moving to a multi-currency business account, three things changed. European clients paid ordinary local transfers into the agency's EUR details; US clients paid domestic USD; inbound fees and delay excuses disappeared. The agency stopped routing software subscriptions and ad spend through its local bank, paying each vendor in that vendor's currency from the matching balance at the mid-market rate. And the external bookkeeper received one clean statement separate from the local bank account, which made quarter-end reconciliation faster and tidier. The honest ledger includes the costs: the agency kept its local bank entirely — payroll, government fees, and cheques do not belong on an international account — and it waited a week for initial document verification before full activation. The founder's summary has not changed since: the international account solved exactly one-third of the company's financial friction — collection, conversion, and small expenses — and he never asked it to solve more.
Wise Business FAQ
Is a Wise Business account worth it in 2026?
If you bill international clients or pay multi-currency suppliers regularly, yes — the mid-market rate, disclosed fees, and local receiving details touch your margin every month. If your business is single-currency and domestic, no feature of the account earns back the setup effort.
How much does a Wise Business account cost?
There is no monthly fee. A one-time setup fee applies at opening in some countries and not others, and each conversion carries a small route-dependent fee displayed before confirmation. Your real cost scales with usage, not with the account existing.
Can freelancers open a Wise Business account?
Yes — sole practitioners can register on the basis of official documentation of their professional activity, while companies use their registration documents. The account must be in the name of a documented business activity, which is what separates its permissions and tooling from a personal account.
What are Wise Business alternatives for international payments?
Airwallex suits companies wanting a broader payments and spend-management stack; Payoneer is strong for freelancers collecting from gig platforms; Mercury serves non-US founders operating US entities. Our three-way comparison covers the details.
Does Wise Business work for US LLCs and UK Ltd companies?
Availability depends on the country of registration, and the platform shows your country's status before you begin. Where available, registered entities such as US LLCs and UK Ltd companies onboard with registration documents and beneficial-owner identification.
How long does Wise Business verification take?
Plan for days to a couple of weeks depending on document completeness and activity type. Submit the full file in one pass — documents arriving in dribs and drabs reopen the review each time and stretch the timeline.
Is Wise Business safe for large transfers?
The company is London-listed, regulated across multiple jurisdictions, and states it runs over seven million fraud checks daily. Sound practice regardless of provider is to split operating liquidity between the international account and your licensed local bank rather than concentrating all working capital on one platform.
Does Wise Business pay interest on balances?
In some regions, the optional Wise Assets feature pays returns on certain currency balances through its European entity. It is opt-in and disabling it removes no core functionality — transfers, receiving details, cards, and invoicing work independently of it.
Our verdict
For cross-border collection and multi-currency supplier payments, Wise Business is one of the strongest instruments available to a small or mid-sized business in 2026, and its value concentrates in three things: the mid-market rate, fees disclosed before you commit, and local receiving details in the currencies your clients actually use. Open it with its limits in view: no credit, no branches, a verification queue measured in days, and country-by-country availability. Run it as the international collection layer above your local bank — which keeps payroll, government payments, and anything paper-based — and the economics show up in the first quarter. And if you want the decision reviewed against your broader business and advisory setup, the Truescho consultant centre offers sessions with advisers you choose yourself.
Sources
- Wise — official Business account page — features and pricing as officially published
- Wise Business official YouTube channel — official product explainers
- Wise announcement of the Chequing account launch in Canada — press release via PR Newswire Canada, 14 September 2026
- WorldFirst — published business account and card reviews during 2026 (cited as market commentary)
- Expatica articles on using Wise for residents in Europe — user-experience coverage, 2026